What if you max a Trump Account for your kid and convert it to Roth at 18?

By Ryan Inman
Published · Updated
The short answer
$90,000 of contributions. $1,000 from the government. Convert it to Roth at 18, never touch it again, and it becomes $4.16 million tax free at 65.
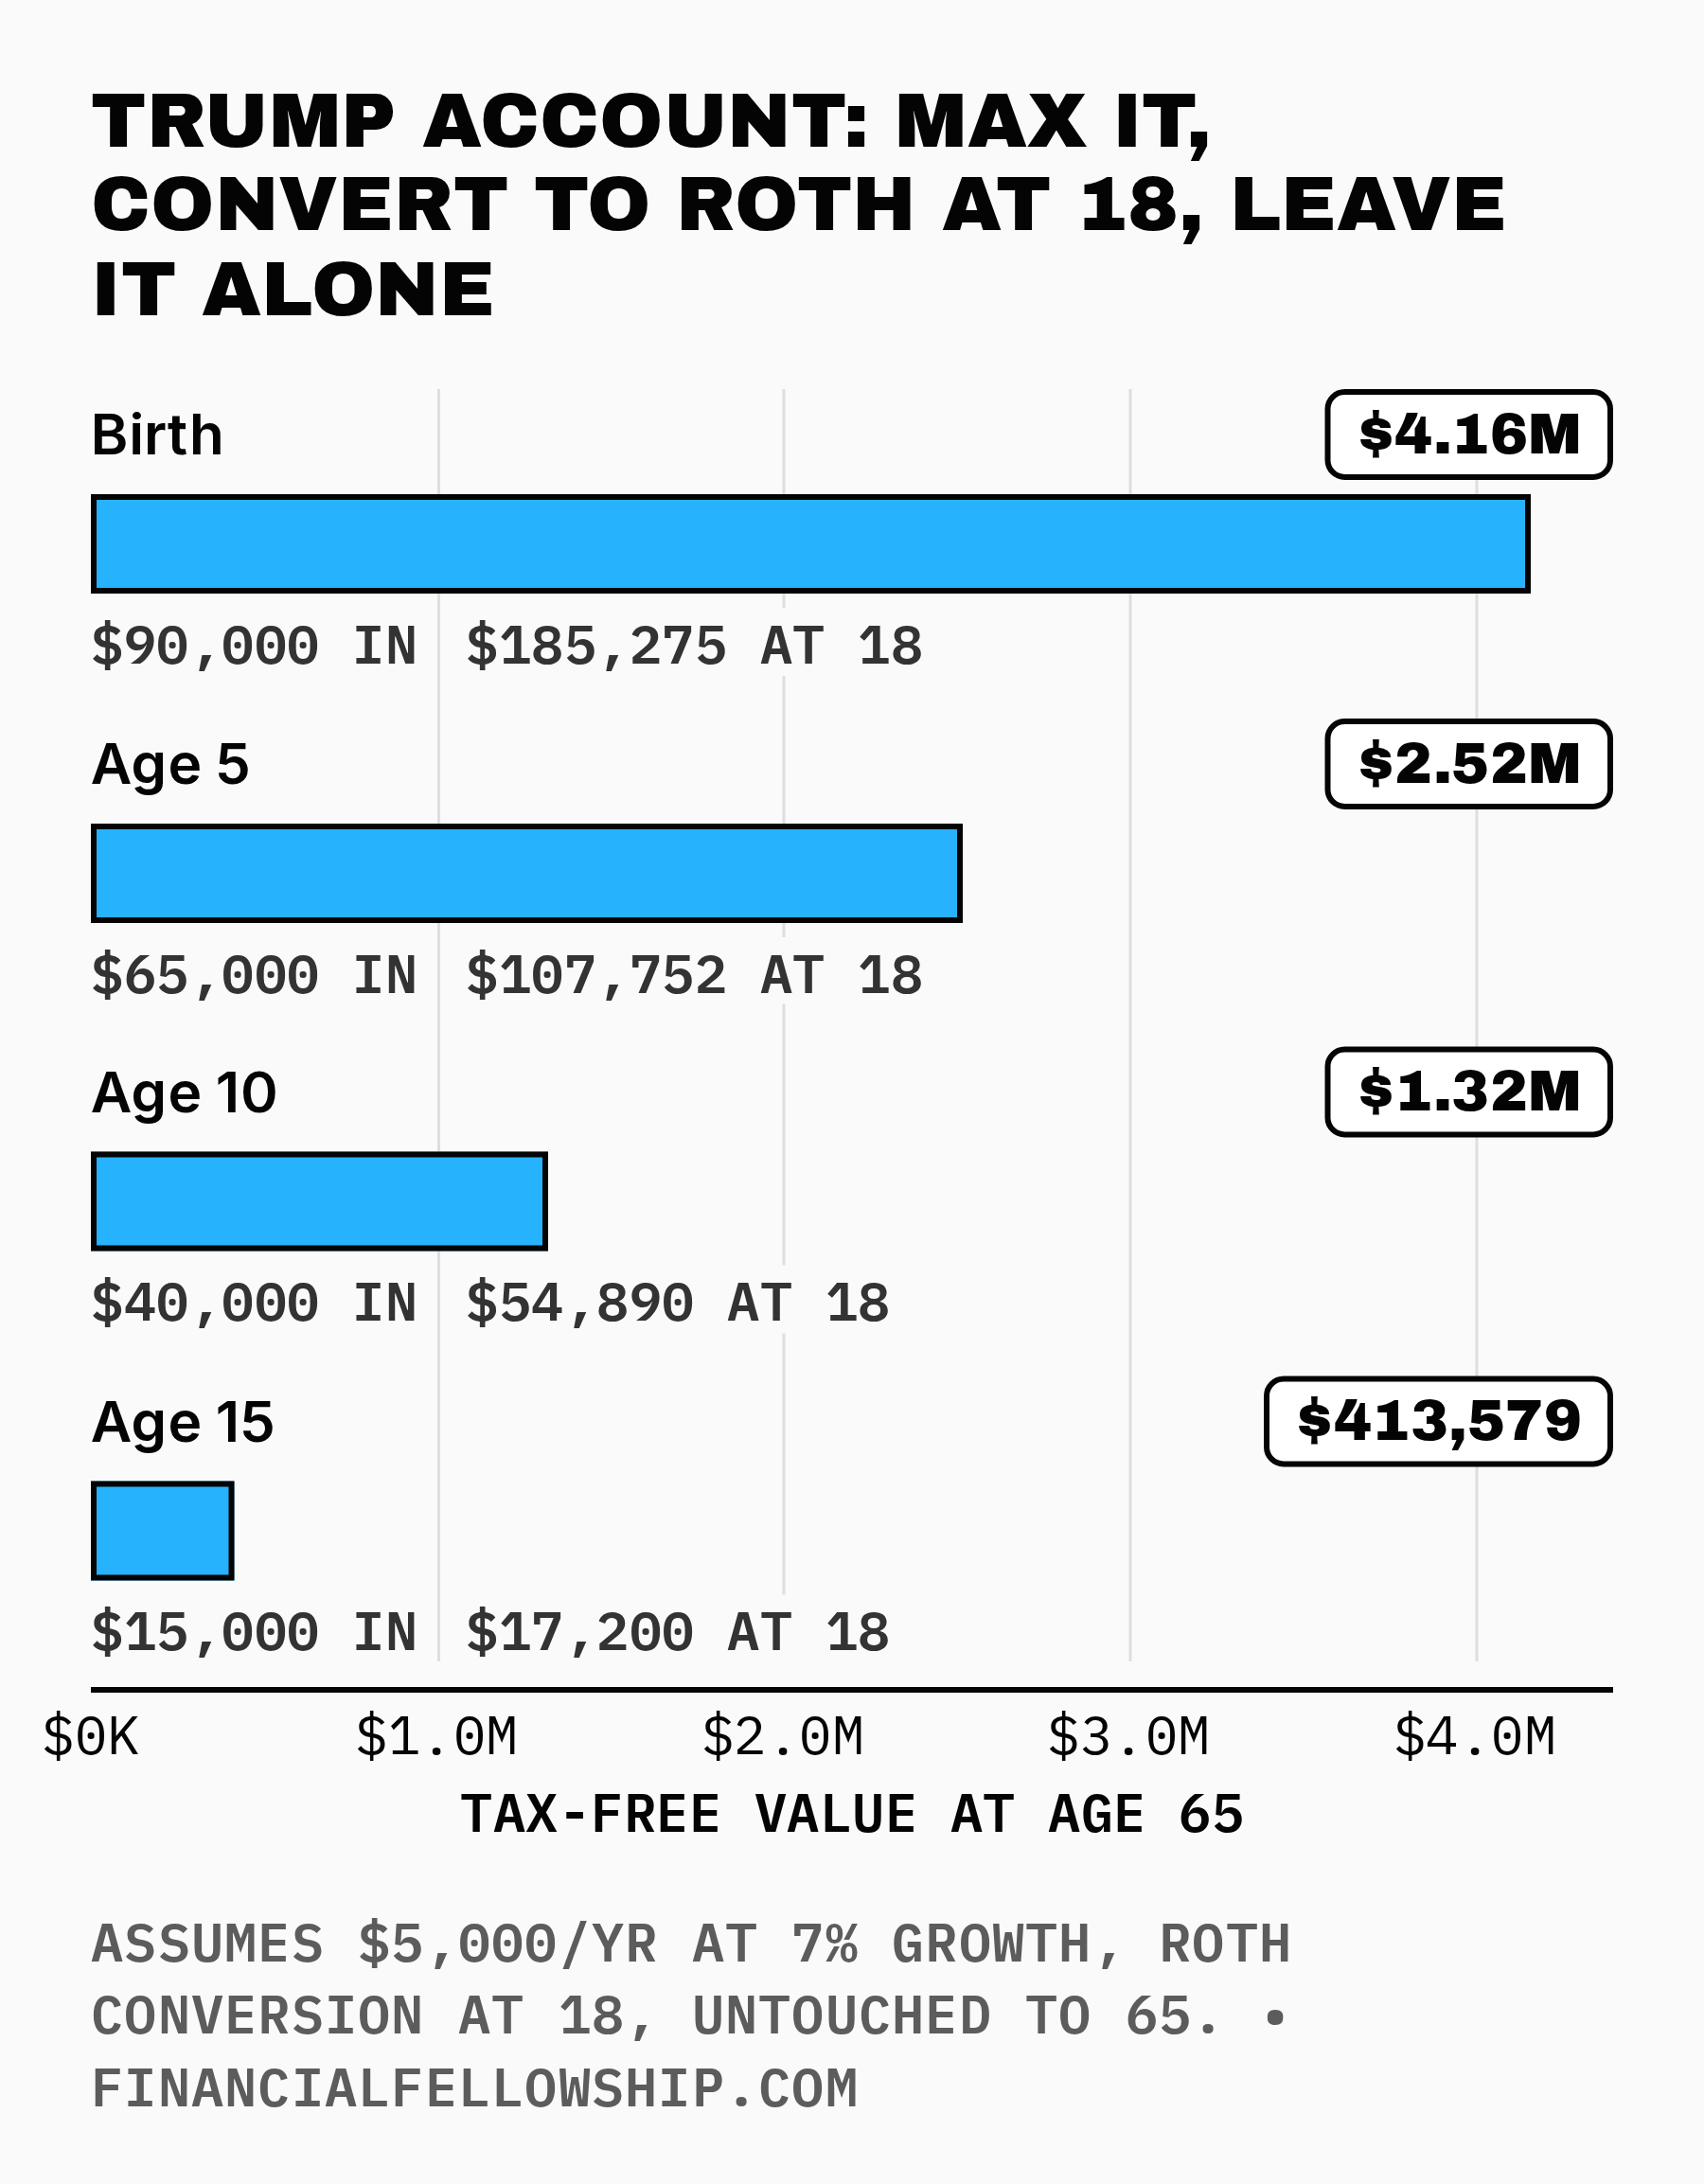
That is not a typo. Here is the new account, the math, and the catch nobody is talking about.
What is a Trump Account?
A new type of IRA for children, created by the One Big Beautiful Bill Act signed July 2025. The basics, from the IRS:
- Any child under 18 with a Social Security number can have one. One account per child.
- Children born 2025 through 2028 who are US citizens get a one time $1,000 federal deposit. The seed does not count against the annual limit.
- Family, friends, and employers can contribute up to $5,000 a year per child through the year the child turns 18. Employers can contribute up to $2,500 of that $5,000. The $5,000 cap is indexed for inflation starting 2028.
- Contributions opened July 4, 2026.
- The money must sit in US stock index funds or ETFs. No individual stocks.
- No withdrawals until 18. At 18, standard IRA rules take over.
The tax treatment is the part that matters. Contributions from family are after tax, so they create basis. The $1,000 federal seed and any employer or charity money is pre tax. All growth is pre tax until it comes out.
The play: max it, convert at 18, let it ride
At 18 the account behaves like a traditional IRA, which means it can be converted to a Roth IRA. The conversion is taxable, but only the pre tax part is taxed: the earnings, the federal seed, and any employer money. Your family's after tax contributions come out as basis and convert tax free, spread pro rata.
An 18 year old with little other income pays tax at the lowest brackets. Then the Roth grows tax free for 47 years. That is the whole play.
The math, by the age your kid starts
Assumptions, stated plainly: $5,000 contributed each year through age 17, 7% annual growth, the $1,000 federal seed for newborns only (2025 to 2028 births), conversion taxed at 2026 single individual rates with the $16,100 standard deduction and no other income, no kiddie tax applying in the conversion year (more on that below), Roth left untouched to age 65.
| Kid starts at | Value at 18 | Tax to convert | Roth after conversion | Value at 65, tax free |
|---|---|---|---|---|
| Birth | $185,275 | $12,130 (6.5%) | $173,144 | $4,163,377 |
| Age 5 | $107,752 | $2,950 (2.7%) | $104,802 | $2,520,042 |
| Age 10 | $54,890 | $0 | $54,890 | $1,319,868 |
| Age 15 | $17,200 | $0 | $17,200 | $413,579 |
Two things jump out. First, the conversion tax is small because most of the account is after tax basis. A newborn's $185,275 converts at an effective 6.5%. Second, starting at 10 or 15, the gain is small enough to fit under the standard deduction, so the conversion costs nothing.
Even the worst seat in the house works. Start at 15, put in $15,000 total, and it becomes $413,579 tax free at 65.
The catch: the kiddie tax follows your kid to 23
Here is what the cheerleaders skip. The kiddie tax does not end at 18. It applies to full time students through age 23. If your 19 year old is a full time college student and still your dependent, unearned income above the annual threshold is taxed at YOUR rate, not theirs.
For a physician household, that is the whole ballgame. Your marginal rate might be 35% or 37%. The table above assumes the conversion is taxed at the child's own low brackets, with no kiddie tax in play. If the kiddie tax applies instead, that 6.5% conversion on a newborn's account can become 30% or more, and the play falls apart.
This is a timing problem with a timing answer. The conversion works best in a year the kiddie tax does not apply: the child is 18 or older, not a full time student, and has little other income. A gap year, a working year before college, or waiting until the kiddie tax window closes can change the answer completely. Run the timing with your CPA before anyone converts anything.
What else can go wrong
- $90,000 of contributions over 18 years is the max case, not the typical case. Smaller contributions scale the ending roughly proportionally.
- The account must stay in index funds. You cannot juice the return with individual stocks.
- Treasury is still finalizing the rules. Contribution mechanics, reporting (including the Form 4547 election), and custodian options are not final yet.
- Congress created this program in 2025. A future Congress can change it.
Should you open one?
| Situation | Answer |
|---|---|
| Newborn or young child, and you can fund $5,000 a year | Contributions opened July 4, 2026, so open one now and automate it. This is the best seat in the house. |
| Kid is 10 to 15 | Still worth it. The conversion is likely tax free and the age 65 number starts around $400,000. |
| 529 vs Trump Account | Different jobs. The 529 is education money with a penalty if it is not used for school. The Trump Account is retirement money that happens to start at birth. Fund both if you can. |
| Convert at 18? | Yes, but time it around the kiddie tax. The conversion year matters as much as the contribution years. |
The main points
- Max it at $5,000 a year through age 17. The earlier you start, the bigger the ending.
- Convert to Roth at 18 when the tax bill is tiny. Most of the account is after tax basis.
- Time the conversion around the kiddie tax, which follows full time students to 23.
- A newborn's $90,000 can become $4.16 million tax free at 65. Even starting at 15 works.
Sources
- Internal Revenue Service, Working Families Tax Cuts (Trump Accounts overview). Working Families Tax Cuts (accessed October 3, 2026)
- Internal Revenue Service, 4 million children signed up for Trump Accounts. 4 million children signed up for Trump Accounts (accessed October 3, 2026)
- Fidelity, Should you convert a Trump Account to a Roth IRA. Should you convert a Trump Account to a Roth IRA (accessed October 3, 2026)
- Kitces, Custodial Account Rules and Trump Accounts. Custodial Account Rules and Trump Accounts (accessed October 3, 2026)
- Cato Institute, Improving Trump Accounts. Improving Trump Accounts (accessed October 3, 2026)
- Vanguard, What to know about the new Trump accounts for kids. What to know about the new Trump accounts for kids (accessed October 3, 2026)
- Morningstar, Trump Accounts vs 529. Trump Accounts vs 529 (accessed October 3, 2026)
Published October 2026. Last reviewed October 2026.